A new law out of Sacramento may not have been on your radar, but it is worth a few minutes of your time. If your home was damaged by smoke but is still standing, this law may change how long you can pause mortgage payments and how quickly your permits move through the system.
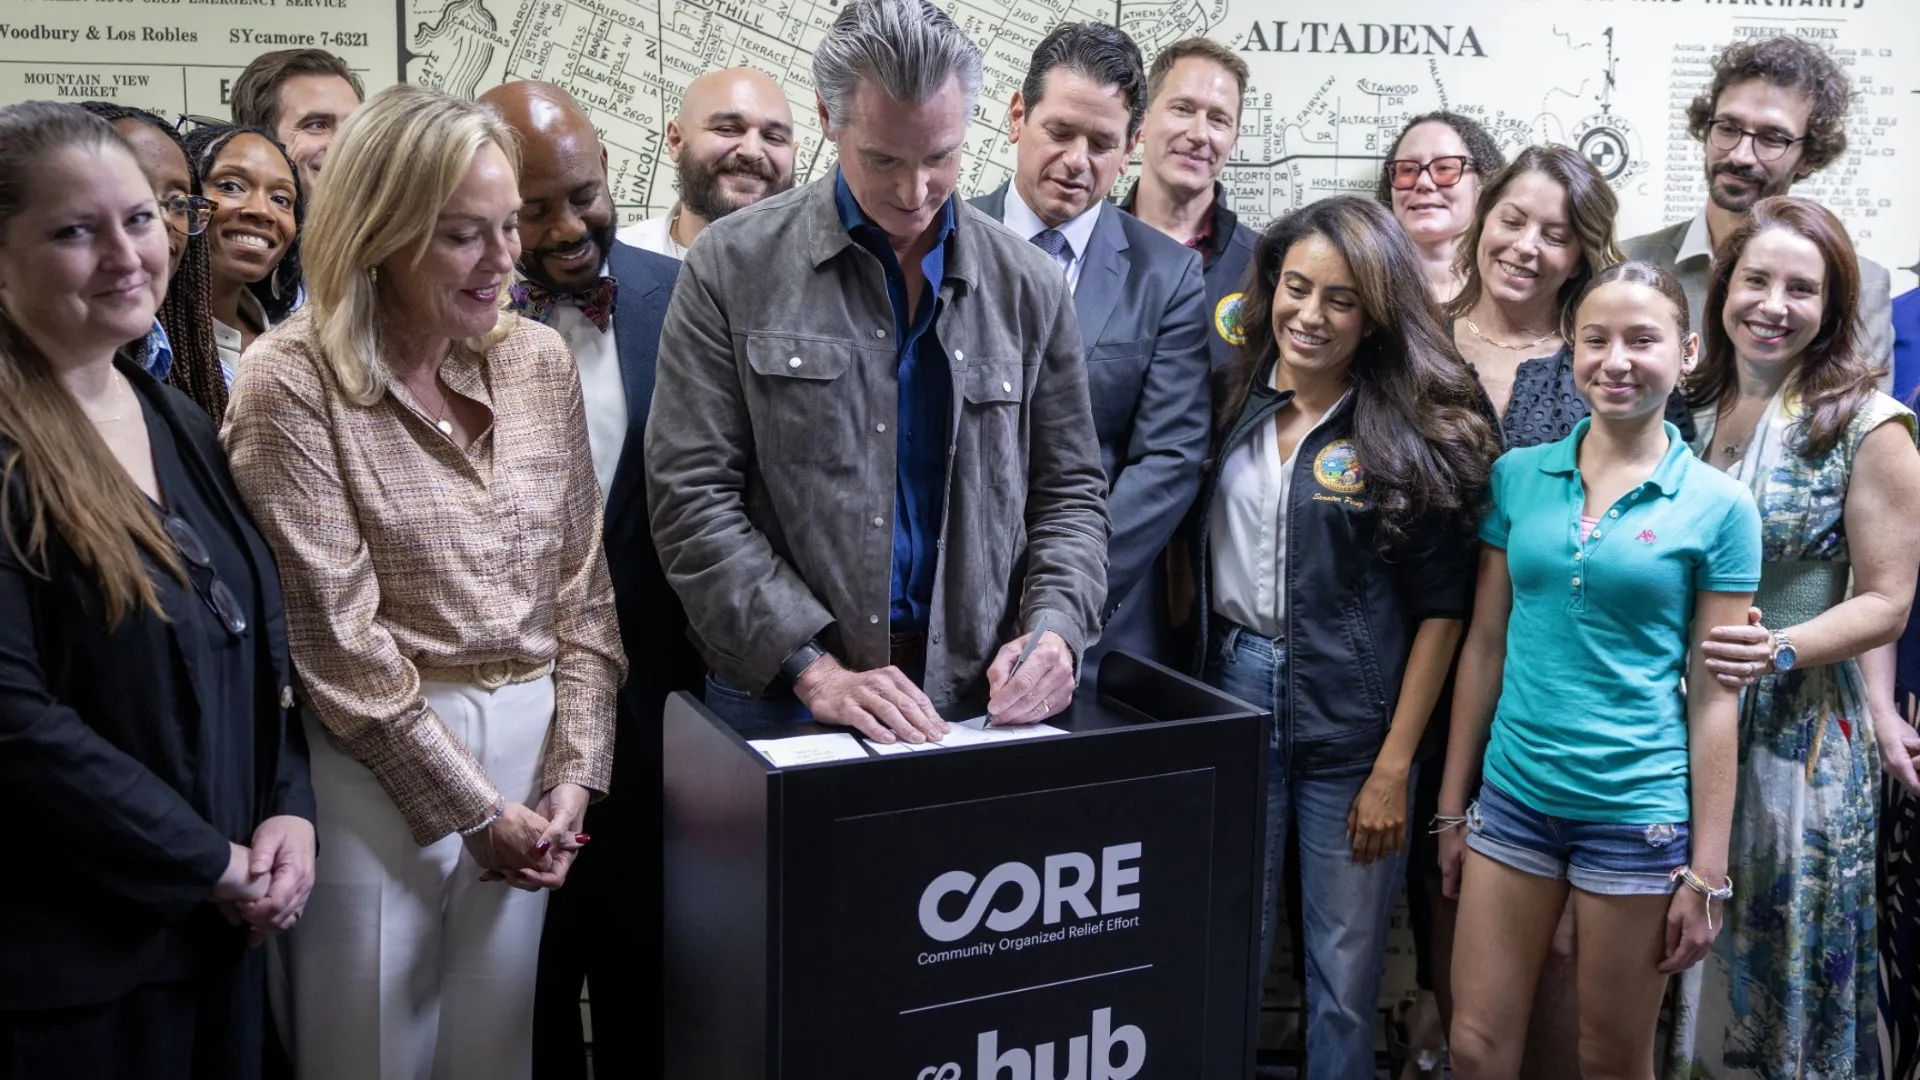
On September 15, 2026, Governor Newsom signed four bills into law in Altadena, alongside survivors, advocates, and the lawmakers who wrote them. Here is what actually changed, and what it might mean for your own rebuild.
What Do the New Smoke Damage Standards Mean for Your Insurance Claim?
For a lot of families, the fire itself was not the only source of damage. Smoke traveled into homes that never burned, and until now, there was no consistent standard for how insurers had to test, clean, or restore those homes.
Assembly Bills 1642 and 1795 changed that. They direct the Department of Toxic Substances Control and the California Air Resources Board to set the state's first science-based standards for testing and remediating lead and asbestos contamination from wildfire smoke, for homes inside a fire's affected zip codes. The law also requires insurers to pay for that testing and remediation, cover full restoration back to pre-loss condition, and keep paying Additional Living Expense coverage until your home is actually cleared as safe to occupy.
The California Department of Insurance estimates more than 13,000 of the roughly 40,000 claims filed after the January 2025 fires involve this kind of smoke damage to homes that never burned. If your claim is one of them, this law gives you something to point to that did not exist, a defined standard, set by scientists rather than left to an adjuster's judgment call.
How Much More Time Do You Have on Your Mortgage Now?
If you are still paying a loan on a house you cannot live in, Assembly Bills 1842 and 1847 are the ones that matter most. They make permanent the mortgage forbearance protections the state first secured directly from lenders after the LA fires, and they double the forbearance window available by law, from 12 to 24 months . Loan servicers are now required to offer borrowers the option to defer missed payments until the end of the loan, rather than demanding a lump sum or pushing a rushed repayment plan.
Alongside these laws, the CalAssist Mortgage Fund is still offering up to twelve months and $100,000 in mortgage relief that survivors do not have to repay. The state's newly appropriated $100 million dollar Disaster Rebuilding Fund is meant to help close the gap between what insurance pays out and what rebuilding actually costs, a gap most of the families we talk with know well.
Does Any of This Actually Speed Up Your Permit?
Since the fires, the state has issued twenty-eight executive orders aimed at cutting the red tape around rebuilding, including suspending certain barriers under the California Environmental Quality Act and the Coastal Act. Local building departments have issued more than 8,450 permits so far, and the state has funded tools like an AI-assisted plan-check system that flags code issues before a homeowner even submits an application.
The state has also funded pre-approved home designs matched to the character of affected neighborhoods, specifically so permits can move faster. Letter Four's own pre-designed home collection is an option for clients looking for a vetted starting point instead of rebuilding from a blank page.
New laws are one more thing to keep track of when you are already carrying a lot. You should not have to sort through them on your own. Our team can walk through where your claim, your loan, and your permit stand today, and what these changes may mean for your property. The first conversation comes with no obligation to go further.
Book a consultation with our team or reach us at (323) 275-1140.
Frequently Asked Questions
What do Assembly Bills 1642 and 1795 change for smoke damage insurance claims?
AB 1642 and AB 1795 create California's first enforceable, science-based standards for testing and remediating lead and asbestos contamination caused by wildfire smoke, for homes within a fire's affected zip codes. Before these laws, there was no consistent statewide standard, and homeowners often had to rely on an insurer's own judgment about whether a smoke-damaged home was safe. Now, the Department of Toxic Substances Control and the California Air Resources Board set the standards, and insurers must pay for testing and remediation, cover full restoration to pre-loss condition, and continue Additional Living Expense payments until the home is verified safe to occupy. If you have a wildfire insurance claim tied to smoke damage rather than fire damage, ask your insurer how these standards apply to your case.
How long can fire survivors now defer mortgage payments?
AB 1842 and AB 1847 doubled the mortgage forbearance window available by law to Los Angeles fire survivors, from 12 months to 24 months. Loan servicers are also required to give borrowers the option to defer repayment of any missed payments until the end of the loan term, rather than requiring a lump-sum catch-up or an accelerated repayment schedule, unless an investor contract prohibits it. These protections are now permanent for future disaster-affected homeowners as well, not just a one-time response to the 2025 fires. Survivors can also still apply to the CalAssist Mortgage Fund for up to 12 months and $100,000 in mortgage relief that does not need to be repaid.
Does fire-resistant or non-combustible construction affect my insurance rate?
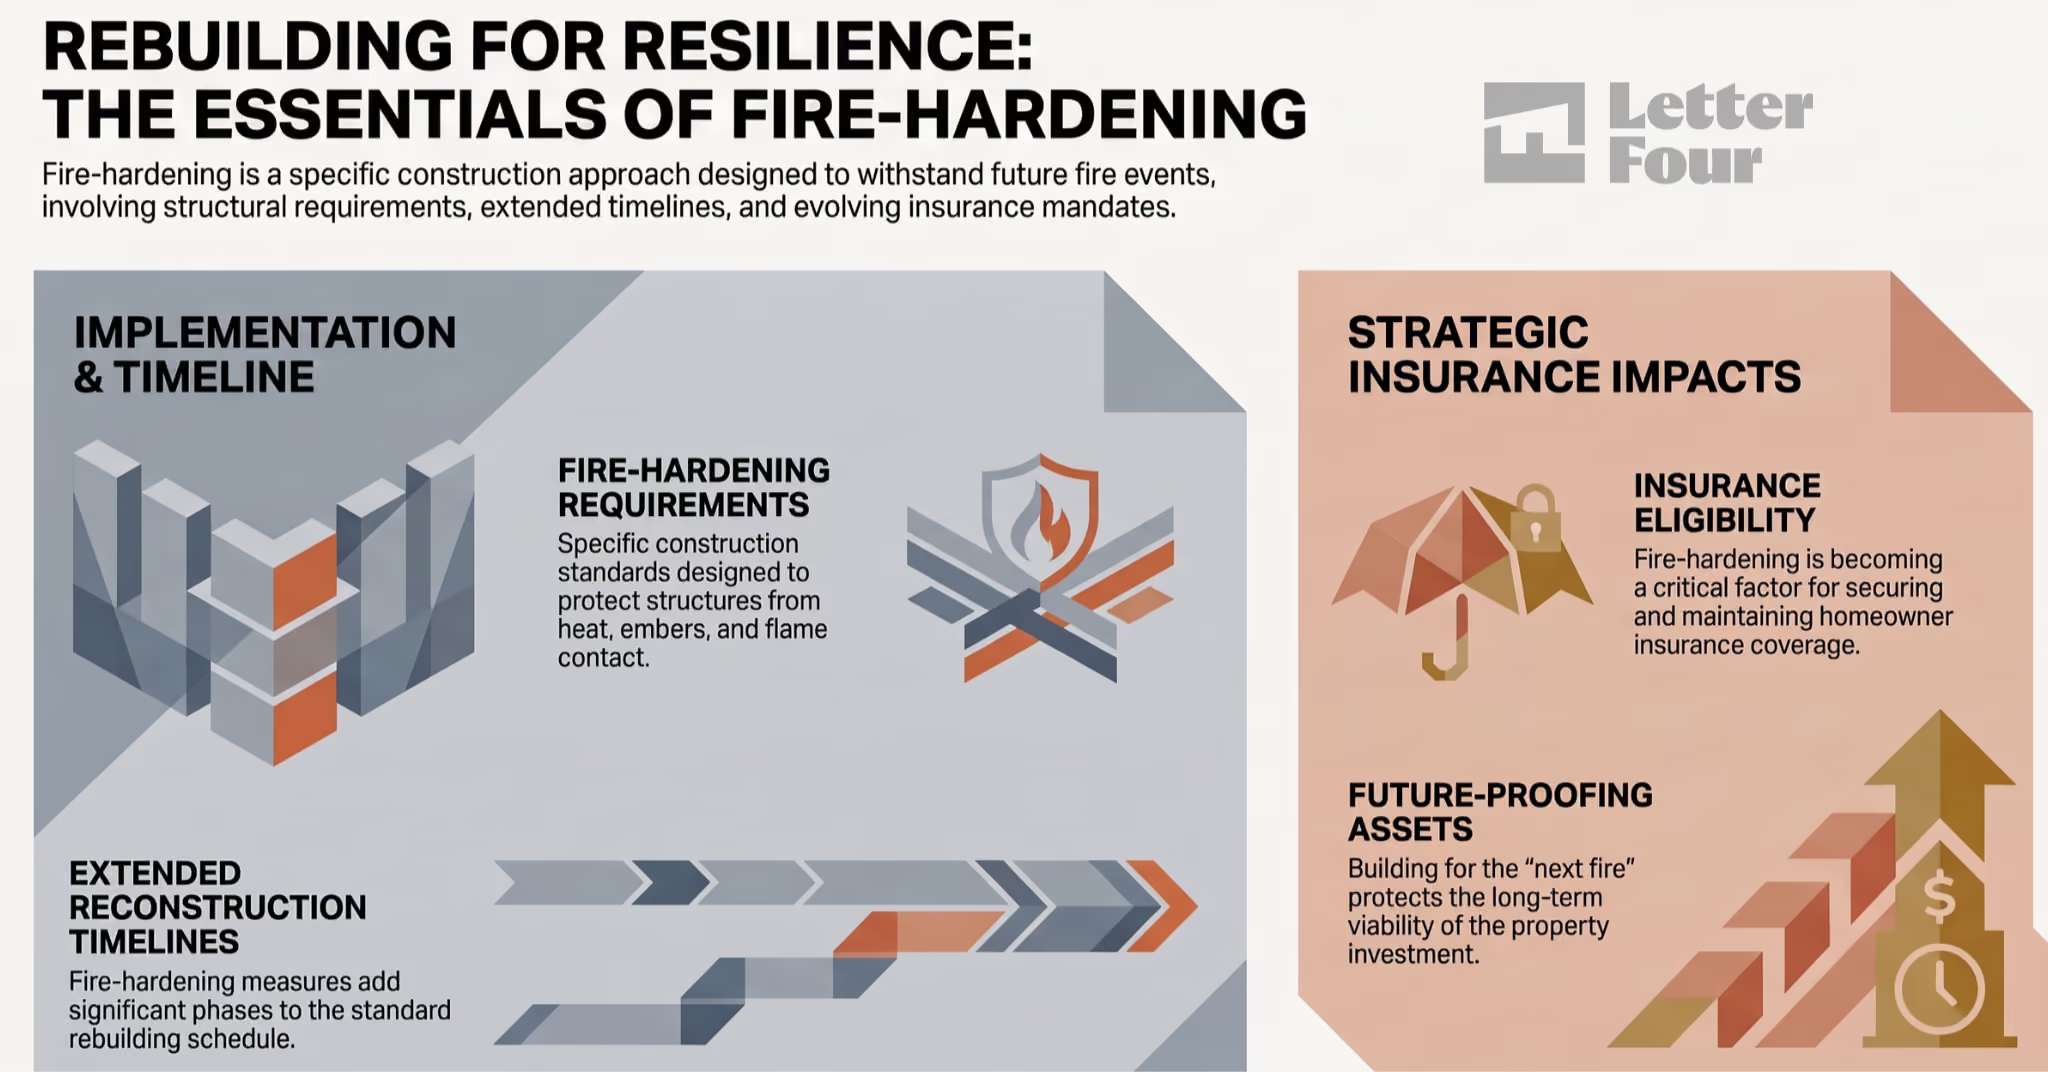
The new legislation focuses on claims and mortgage relief rather than directly setting insurance rates for non-combustible construction, but the two are connected in practice. Insurers increasingly factor wildfire-resistant building choices, such as non-combustible siding, ember-resistant vents, and defensible landscaping, into underwriting and renewal decisions in high-risk zones. Building to current Wildland-Urban Interface code, and documenting those upgrades clearly, can support a stronger insurability case even where it does not guarantee a specific rate. If insurance cost and renewal risk are driving your rebuild decisions, it is worth asking your architect or design-build team to build a materials specification you can hand directly to your insurer.
How fast are wildfire rebuild permits actually moving in Los Angeles right now?
As of this month, local building departments have issued more than 8,450 permits for LA fire rebuilds, a pace the state attributes to 28 executive orders streamlining environmental review, debris removal, and permitting since the 2025 fires. The state has also funded an AI-assisted plan-check tool that flags code issues before a homeowner submits an application, along with pre-approved home designs meant to move through review faster than fully custom plans. Actual timelines still vary by jurisdiction, lot condition, and how complete your submitted plans are, so ask your design-build team for a permit timeline specific to your address rather than a citywide average. According to Morgan Miller, a designer at Letter Four, “Permitting takes time! Our team is dedicated to working closely with AHJs (Agencies Having Juristication) to ensure a smooth and expedient process, helping shorten lead times and, ultimately, getting our clients back into their homes as quickly as possible. Even when everything goes according to plan, permitting a fire rebuild can take months. ”
Should I hire a design-build firm instead of a separate architect and contractor for my fire rebuild?
Either approach can work, but a design-build firm’s services keeps architecture, permitting strategy, and construction under one accountable team, which matters most when the rules themselves are changing. With policy shifting around insurance claims, mortgage forbearance, and streamlined permitting, someone on your project needs to be tracking those changes and adjusting your plans and paperwork accordingly. A separate architect and contractor can still coordinate well, but that coordination has to be actively managed, usually by you. For families already stretched thin by a rebuild, having one team responsible for the whole process tends to reduce the number of things that fall through the cracks.
Source: Office of Governor Gavin Newsom, “Governor Newsom Signs Wildfire Recovery Package to Strengthen Protections and Focus on Rebuilding for Survivors,” September 15, 2026. Bill numbers, funding figures, and claims data are as reported in that release; confirm current implementation status with your insurer, loan servicer, or an attorney before relying on specific terms.